Penberthy Newsletter
Volume Two | April 2026
Insight Matters
We’re keeping you informed with the latest insights and advice.
Not all costs are created equal.
The Fire Service Levy is changing. Here’s what it means for your business
From 1 July 2026, changes to the Fire and Emergency New Zealand (FENZ) levy will come into effect.
You contribute to the FENZ levy if you insure:
- Your commercial property
- Your contract works
- Your home
- Your contents
- Certain material damage risks
On paper, it’s just another line within your insurance premium. But in reality, it’s one of the few costs that directly connects what you insure… with the services that protect it.
The levy funds vital fire and emergency services, ensuring that, every day across New Zealand, fire and emergency crews can respond to incidents that can stop a business in its tracks or wipe out someone’s home. From fires to floods, vehicle accidents, hazardous spills, and more.
And while there’s been increased visibility recently around the pressure on those services, one thing hasn’t changed: Their role in keeping businesses, assets and communities safe is critical.
What’s changing and why it matters commercially
The structure of the levy is being updated. For many businesses, commercial and residential property owners and individuals this is more than a technical change. In fact it has the potential to materially impact total insurance spend.
If you own vehicles, commercial property, rural property, or mixed-use buildings, your levy charges may change more noticeably. The levy you pay may increase or decrease depending on your insurance type and sums insured.
Key shifts include:
- Commercial & rural property:
The levy rate changes from 11.95c per $100 sum insured to 7.76c per $100 sum insured. However, the main notable change is under the revised structure, the FENZ levy will be based on the replacement value sum insured rather than indemnity value.
- Plant, Machinery & Equipment:
– Plant, machinery and equipment not classified as vehicles will be payable on the 7.76c per $100.00 SI rate
– Items classified as vehicles will attract the flat vehicle levy of $25 per vehicle
- Mixed-use properties
(i.e. residential & non-residential):
The levy is calculated based on the split of residential occupancy and business occupancy.
- Residential policies:
The maximum levy reduces slightly.
- Residential Home charge:
This will be capped at $107.40, (down from $119.50)
- Home Contents:
The levy is calculated based on the split of residential occupancy and business occupancy.
- Motor vehicles:
The maximum levy reduces slightly.
- Some items that were previously exempt (such as fences, water tanks, livestock, forestry and aircraft) will now attract a levy.
What this means for you
It’s easy to overlook levies as just another charge, but as Head of Fire & General, Richard Livngston, says “They fund something every business and property owner relies on, whether directly or indirectly – the ability to respond, recover, and rebuild when something goes wrong. This is where advice becomes commercially important and not just informative.”
The most important shift isn’t just the rate change. It’s the move toward alignment between insured value and levy contribution and for businesses, this creates two key implications:
- If your sums insured don’t accurately reflect replacement value, the levy may highlight that quickly.
- Businesses with large property portfolios, contract works, or high declared values may see noticeable changes in cost, even where rates have reduced.
In short, this is less about a price change and more about how your levy is structured.
It should also be noted that the changes mean that where some businesses were used to completing a FENZ declaration to decrease the FENZ indemnity value on a commercial building, we are no longer permitted to do this and the FENZ value needs to match the reinstatement value. This may result in a higher levy premium in most cases (potentially mitigated by the drop in standard FENZ levy).
We will automatically apply the correct levy to your policies from 1 July 2026 and we are here to help explain what this means for your cover.
Where Penberthy adds value
At Penberthy, we’re proactively working with clients to:
- Review how levy changes will flow through their insurance programme
- Ensure sums insured are accurate and defensible
- Identify where structure or cover adjustments can mitigate unintended cost increases
- Use this as an opportunity to strengthen overall programme design (not just react to the levy)
The Bottom Line
Changes like this don’t just affect premiums. They affect how well your business and other assets are protected, and how efficiently you’re paying for it.
If you would like more information on how the new levy will apply to your insurances. Please touch base with us.
Because sound advice is about clarity and confidence.
Your Safety Net in the Sun
Why Medical Insurance Matters for Melanoma Checks
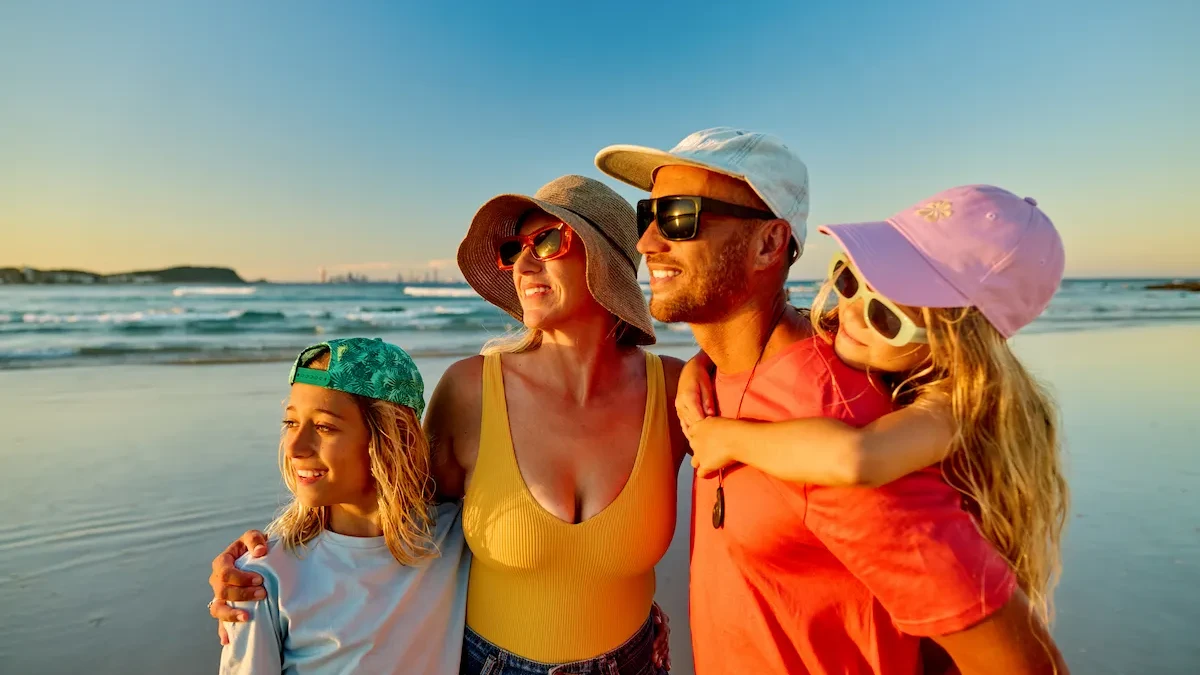
We love the New Zealand sun with our long summers, beach days, backyard cricket and early morning walks. But the reality is New Zealand has one of the highest melanoma rates in the world.
Our outdoor lifestyle, high UV levels, and fair-skinned population mean skin cancer is something many Kiwi families will encounter in their lifetime. And while sun smart habits are essential, there’s another layer of protection that often gets overlooked: financial preparedness through insurance cover.
Because when it comes to melanoma, early detection and speed matter.
The power of early detection
Melanoma is one of the most serious forms of skin cancer, but when caught early, outcomes are dramatically better.
That’s why regular skin checks are so important.
A full-body skin examination with a trained GP or dermatologist can identify suspicious moles or lesions long before they become life-threatening. Many clinics now offer mole mapping technology, allowing changes to be tracked over time for added peace of mind.
For many New Zealanders, especially those with high sun exposure, a baseline skin check and ongoing monitoring is simply part of being proactive about health.
Prevention is the first layer of protection.
Early detection is the second.
And the third?
The part people don’t always think about
Public healthcare in New Zealand provides excellent care, particularly for urgent or advanced cases. But access to specialist dermatology can involve waiting lists, particularly for non-urgent assessments.
Yes you can go private for consultations and mole mapping appointments and, if needed, follow up biopsies, excisions and follow-up procedures. But it all adds up.
If melanoma is diagnosed, treatment pathways may then involve surgery, oncology consultations, and in some cases advanced therapies.
The difference often comes down to access and speed.
When something doesn’t look right, most people don’t want to wait. And they don’t want financial considerations to delay a decision.
How medical insurance becomes your extra layer
Medical insurance isn’t about expecting the worst. It’s about removing barriers when you need to act and for many families this means peace of mind, in a stressful situation.
Depending on the policy, medical insurance can help cover:
- Specialist dermatology consultations
- Mole mapping and surveillance (where included)
- Diagnostic biopsies and surgical procedures
- Follow-up treatments
- Faster access to private care
If something changes, you can book the appointment. If a procedure is needed, you can proceed without hesitation. If specialist treatment is required, you have options.
It’s an extra layer of protection, alongside sunscreen, hats, and regular skin checks.
We can’t change the intensity of the New Zealand sun. But we can take steps to protect ourselves. That starts with being sun smart. It continues with regular skin checks. And it includes reviewing whether your medical insurance cover aligns with the realities of where we live.
At Penberthy, we work alongside families to ensure their protection keeps pace with their lives. Medical insurance isn’t one-size-fits-all and not all policies offer the same level of access or coverage.
If you’re unsure what your current cover includes, or whether it provides adequate protection for skin checks and treatment, we’re here to help you review it.
Because peace of mind in the sun isn’t just about SPF. It’s about knowing you have a safety net if you ever need it.
The value you don’t see in your insurance
The fringe benefits that make a difference
When people think about insurance, they often focus on the obvious. What’s the premium? What’s covered? What’s the payout?
But some of the most valuable parts of your cover aren’t listed in the policy wording at all.
They’re the fringe benefits. The softer, often intangible advantages that sit alongside your insurance. And in many cases, they’re the things that make the biggest difference when life takes an unexpected turn.
Many insurance providers now offer additional benefits that go well beyond the policy itself. It’s a shift from reactive protection to proactive support.
It’s important to note that every policy and policy provider is different, so it’s important we look at what’s best for you and provide sound advice based on that. But, essentially there are four types of fringe benefits classified in legislation:
- Motor vehicles available for private use
- Fleet risk management
- Roadside assist
- Free building Electrical assessments
- Low interest/interest free loans
- Free, subsidised or discounted goods and services
- Employer contributions to sick, accident or death benefit funds, superannuation schemes and specified insurance policies
The other type is unclassified benefits. These are benefits provided by employers that are not specified in legislation.
Smart benefits for a more engaged team
Many companies now adopt a well-structured employee benefits policy. It can help with staff attraction and retention and productivity, among other things.
These can include:
- Health and wellbeing programmes
- Mental health support services
- Discounts and rewards for healthy living
- Early intervention services to support recovery
At Penberthy, we design tailored group insurance solutions for businesses with ten or more employees that boost staff satisfaction, support well-being, and enhance the employers brand. These form part of their employee benefits package and can include:
- Group Medical Insurance
As an employer you pay discounted premiums to provide staff with access to private medical treatment, often covering pre-existing health conditions without exclusion. This helps your employees avoid public health system delays, facilitating quicker diagnosis, specialist consultations, and treatments, and supporting faster return to work.
- Group Life Insurance
This can cover death and terminal illness, with optional extensions for total permanent disablement and critical illness (trauma) insurance. This insurance provides peace of mind to your employees and their families through lump sum payments if these events occur.
- Group Income Protection
This provides a monthly income replacement benefit (up to 75% of their salary) if an employee is unable to work due to illness or injury, ensuring financial stability during recovery.
The real value of fringe benefits
Fringe benefits might not always be front of mind, but they’re often where the real value lies, when things go wrong. But by then, it’s too late to revisit your choices. That’s why understanding what sits around your policy is just as important as understanding what sits within it.
In many cases, it’s these “extra” benefits that shape the overall experience of your insurance. They help define how supported you feel, how quickly you recover, and how confidently you can move forward.
The Bottom Line
Our role at Penberthy is to make sure nothing is left to chance. We look beyond the policy itself and work with you to ensure your cover reflects not just your risks, but your reality and the right combination of benefits that align with your needs, your stage of life and/or business, and your future plans.
We want to ensure your insurance delivers real value, not just theoretical protection, so you can move forward with confidence. Because, when you know you’re protected, you’re often more confident to make decisions you might otherwise hesitate on.
The Power of Discipline and Relationships
Meet Ilan Wisenberg
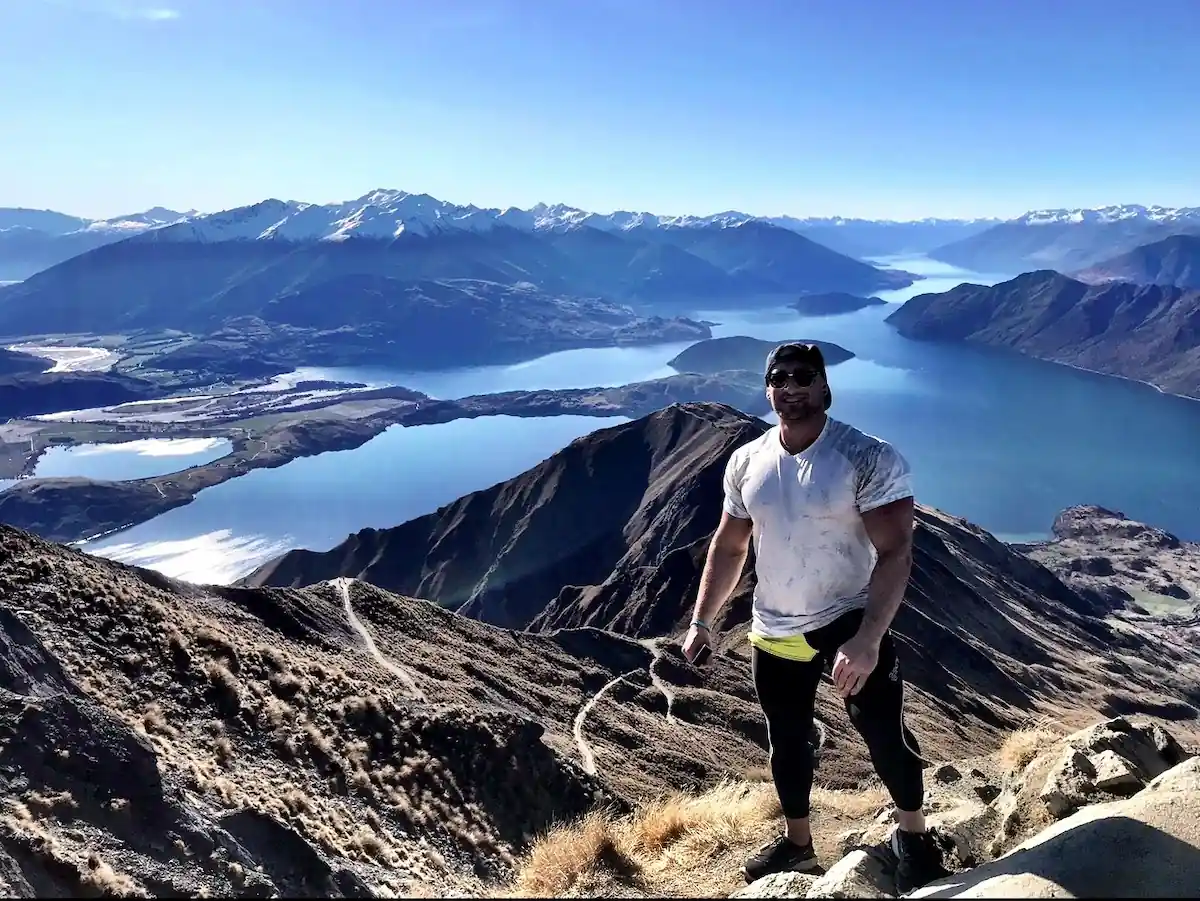
Nearly two years into his journey with Penberthy, and approaching 20 years in the insurance industry, Ilan Wisenberg brings both experience and energy to his role.
Having worked across all areas of insurance over the years, Ilan has developed a broad, practical understanding of the industry. But it wasn’t just the work itself that drew him to Penberthy.
It was the opportunity to build genuine relationships.
“I’ve never been interested in just being a voice at the end of the phone,” Ilan says. “What I value is face-to-face connection, understanding a client’s business properly, and being someone they trust.”
His client portfolio reflects that diversity. From manufacturing, construction and property owners portfolios, no two days are the same. For Ilan, that’s part of the appeal. Each industry brings its own complexities and opportunities, and he enjoys taking the time to truly understand how each business operates before offering advice.
That desire to understand, not just transact, is a defining part of his approach.
Outside the office, Ilan’s discipline and consistency is equally evident. A committed personal training enthusiast, he trains twice a day, six days a week. That’s right! Cardio in the morning and weights in the afternoon.
For Ilan, fitness isn’t just physical. It’s mental clarity. It’s consistent routine and it’s pure dedication. Much like his approach to his work. He believes in always being prepared, proactive, consistent and willing to go the extra mile.
“Health and fitness is important downtime for me,” he says. “It keeps me sharp, balanced, and ready to show up properly in all aspects of my life, including for clients and the team at Penberthy.”
Ilan values the culture he works within. He describes the Penberthy team as supportive, grounded, and genuinely family-oriented. A place where strong values aren’t just written on a wall, but embedded in how people treat each other and their clients.
And ultimately, that’s what clients experience:
Consistency. Commitment. Care.
For Ilan, strong relationships, like strong performance, aren’t built overnight. They’re built through discipline, trust, and showing up every day.
Articles of Interest
Sound advice is what we love to share, every day. These articles might be of interest to you.
KiwiSaver:What Actually Happens at 65?
For many Kiwis, turning 65 feels like a milestone. It’s the age when KiwiSaver “kicks in” and retirement suddenly becomes very real.
Reviewing Your Will: A Simple Step That Can Make a Big Difference
A new year often brings a natural moment to pause and plan ahead. We think about goals, finances, family, and the year in front of us.
We believe good advice turns complexity into clarity — and that’s what Insight Matters, our regular newsletter, is here to deliver. We hope you have found it informative. If there is anything in this newsletter that you would like to discuss further, please contact us today.
Disclaimer: The information in these articles is for general purposes only and doesn’t constitute financial, legal, or professional advice. Please consult one of our financial advisers or brokers for advice tailored to your specific situation.